On this page
Oak Creek Auto Insurance: Get Covered for Local Driving Today
If you drive in Oak Creek, Wisconsin, and need auto insurance, whether you are shopping for a first policy, adding a teen driver, replacing lapsed coverage, or filing an SR-22, this page walks you through what Wisconsin law requires, what optional coverages make sense for local driving patterns, and how to request a quote.
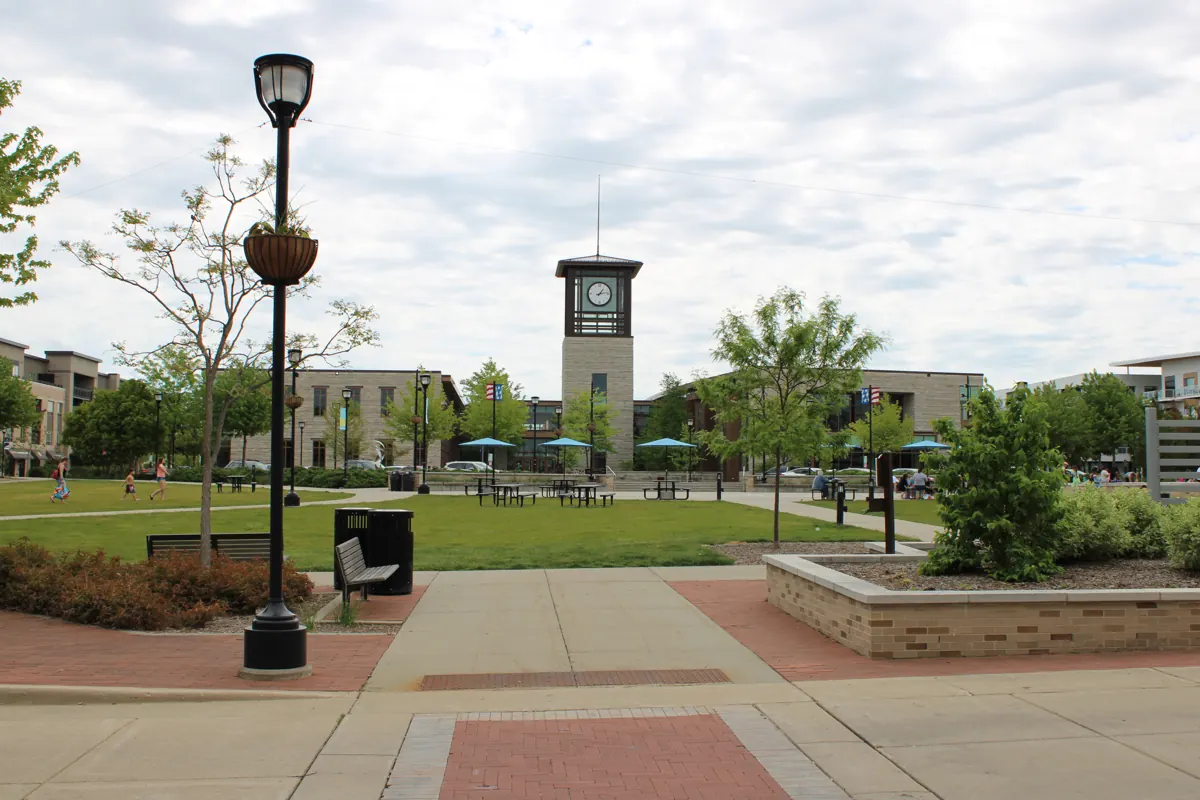
Photo: Michael Barera, CC BY-SA 4.0. Resized and converted to WebP.

Oak Creek sits in Milwaukee County along the I-94 corridor, with daily commuters heading north into Milwaukee or south toward Racine. Residents run errands around Drexel Town Square, drive South Howell Avenue for work and shopping, and many hold jobs near Milwaukee Mitchell International Airport. Lake Michigan’s proximity brings winter ice, lake-effect snow, and hail that factor into coverage decisions.
WisconsinAutoInsurance.com, operated by Drivers Insurance Agency, Inc., helps Oak Creek drivers compare Wisconsin auto insurance options by phone and online. There is no local walk-in office; all quoting and service happen remotely. To get started, request a quote online or call (844) 317-1313.
Why Oak Creek Drivers Choose WisconsinAutoInsurance.com
Oak Creek households include families with teen drivers, airport-area commuters working irregular shifts, retirees, and residents who just moved from another state. Each situation creates different coverage questions. WisconsinAutoInsurance.com is operated by Drivers Insurance Agency, Inc., a Wisconsin-licensed independent agency. Independent agents can compare available participating-carrier options and explain differences; no particular price or outcome is guaranteed.
Because all quoting and service are handled by phone and web forms, Oak Creek drivers do not need to take time off work or drive to a Milwaukee office. This setup fits people who work airport shifts, rotate schedules, or simply prefer handling insurance from home.
Why Oak Creek Trusts WisconsinAutoInsurance.com
The agency focuses on Wisconsin auto insurance law and requirements, not a multi-state generalist approach.
-
Licensed in Wisconsin and focused on WI auto coverage for customers across the state.
-
References and follows consumer guidance from the Wisconsin Office of the Commissioner of Insurance when explaining policy requirements.
-
Regularly helps drivers who commute in the Milwaukee region, including Oak Creek residents traveling I-94, South 27th Street, and routes into Racine County.
-
An agent can explain claim-reporting steps, while the insurer handles claim decisions under the policy.
-
Quotes are customized to each driver’s situation. A quote request does not bind coverage or guarantee acceptance; coverage begins at the effective date and time confirmed by an authorized agent or insurer, subject to binding and payment requirements.
What Makes Our Oak Creek Auto Insurance Help Different
Oak Creek drivers often need to understand the gap between Wisconsin’s state minimums and what a lender or lease company requires. They also need plain-language explanations of SR-22 filings, household driver rules, and how winter weather affects coverage decisions. Auto insurance quotes should clarify the extent of coverage and deductibles to ensure adequate protection; that is what conversations with this agency focus on.
The agency can often assist drivers with clean records and those with tickets, accidents, or coverage lapses. Not every driver will qualify with every insurer, but as an independent agency, the team can explore options across multiple companies. Conversations are no-pressure and informational. Oak Creek drivers can compare before deciding.
Oak Creek Auto Insurance Coverage Options
All Wisconsin auto insurance policies must meet state law minimums, but Oak Creek households can choose higher limits and extra protections based on how and where they drive. Coverage types in Wisconsin include liability, comprehensive, collision, and uninsured motorist coverage. Below is what each one does, what it excludes, and why it matters locally.
Wisconsin Liability Coverage for Oak Creek Drivers
Liability coverage pays for injuries and property damage you cause to others. It does not pay to repair your own vehicle.
Wisconsin requires minimum liability coverage for auto insurance: $25,000 bodily injury per person, $50,000 bodily injury per accident, and $10,000 property damage (commonly written as 25/50/10). These limits can fall short in a serious crash on I-94, where medical bills and vehicle damage from a multi-car collision can exceed $50,000 quickly. Drivers should consider higher liability limits than Wisconsin’s state minimums for better financial protection, especially Oak Creek homeowners whose personal assets could be exposed in a lawsuit after a crash. Coverage for injuries to household members depends on the applicable coverage and policy terms.
Uninsured Motorist (UM) and Underinsured Motorist (UIM) in Wisconsin
Wisconsin requires uninsured motorist bodily injury coverage with at least $25,000 per person and $50,000 per accident. UM covers bodily injury to you, family members, and passengers in your vehicle when another driver has no liability insurance or in a hit-and-run.
UM does not pay for damage to your vehicle. It also does not cover deer strikes, hail, theft, or weather losses. Those fall under collision or comprehensive, subject to policy terms.
Underinsured motorist (UIM) coverage is optional in Wisconsin. If you add it, state law sets minimum limits of $50,000 per person and $100,000 per accident. UIM may cover eligible injury losses when the other driver meets the policy definition of underinsured; limits, offsets and other policy terms apply. For Oak Creek drivers who spend daily time on I-94 at highway speeds, UIM provides a layer of protection when another driver carries only the state minimum.
Medical Payments (MedPay) in Oak Creek Policies
Wisconsin insurers must offer Medical Payments coverage with at least $1,000 in benefits, though drivers can decline it. MedPay helps pay medical and funeral expenses for you and your passengers, regardless of who caused the crash, up to the policy limit.
A practical example: after a fender-bender leaving Drexel Town Square, MedPay can help cover emergency room copays or ambulance charges that health insurance does not fully absorb. MedPay is separate from health insurance. It can supplement deductibles and copays but is not a substitute for full medical coverage.
Comprehensive and Collision for Oak Creek Vehicles
Wisconsin law does not require collision or comprehensive coverage. Most lenders and leasing companies, however, require both while there is an outstanding loan or lease.
Collision coverage helps pay to repair or replace your vehicle after a crash, regardless of fault, subject to your deductible. Comprehensive coverage helps with certain non-crash losses: theft, fire, vandalism, animal strikes (deer are common in southeastern WI), hail, and some weather-related damage, always subject to policy terms and deductibles. Comprehensive and collision coverage protects against theft or damage from accidents or severe weather.
UM coverage does not cover vehicle damage. Oak Creek drivers concerned about winter ice near Lake Michigan or parking-lot damage near shopping areas typically consider collision and comprehensive for that protection.
Claims are generally settled on the vehicle’s actual cash value. When repair costs exceed a large portion of the vehicle’s value, the insurer may declare the vehicle a total loss. Higher deductibles can lead to lower monthly premiums but require emergency funds for coverage when a claim occurs.
Optional Coverages Oak Creek Drivers Often Consider
Several optional features may be available depending on the insurer:
-
Roadside assistance: Useful for breakdowns on I-94 or Ryan Road during winter, when tow wait times can increase during storms.
-
Rental reimbursement: Helps cover the cost of a rental car while your vehicle is in the shop after a covered claim.
-
Towing and labor: Covers tow charges and on-scene labor costs.
Ask during your quote which options are available from the insurers the agency works with. Discounts may include safe-driver, multi-car, home and renters bundles, and good-student discounts, depending on the carrier.
Choosing the Right Coverage for Oak Creek Driving
Coverage decisions depend less on abstract risk categories and more on daily life in Oak Creek. Below are common scenarios local drivers face.
Commuters on I-94 and Airport-Area Workers
Many Oak Creek residents commute north on I-94 into Milwaukee or south toward Racine, with others traveling South Howell Avenue and South 27th Street daily. Drivers who spend hours at highway speeds face different exposure than someone who only drives to a neighborhood store. Higher liability limits and collision coverage are worth evaluating for frequent commuters.
Workers near Milwaukee Mitchell International Airport sometimes park in large lots for extended shifts. Vehicles parked in high-traffic lots for 8-10 hours face theft and vandalism exposure that comprehensive coverage addresses, subject to policy terms.
Families, Teen Drivers, and Household Vehicles
Insurers usually consider all licensed drivers in an Oak Creek household when pricing a policy, including teen drivers attending Oak Creek High School or nearby colleges. Adding a teen driver increases premiums because of the statistical risk profile associated with new drivers.
Review each household vehicle’s coverages and limits, since its value, financing and use may differ. Families who carpool to youth sports or activities around Drexel Town Square or lakefront parks should review liability limits and UM/UIM to make sure protection matches their regular passenger load.
Garaging, Parking, and Oak Creek Regulations
Insurers care where the car is primarily garaged, meaning where it is kept overnight. An Oak Creek address in Milwaukee County carries different risk factors than a rural Wisconsin address, based on traffic density, theft patterns, and weather exposure.
Oak Creek has specific parking regulations that affect where vehicles sit overnight, especially during winter months. Residents can review local parking rules through the city’s official parking page. Street parking restrictions during winter may push vehicles into driveways or garages, which can reduce exposure to hit-and-run damage or theft compared to curbside parking.
Financed and Leased Vehicles in Oak Creek
The state does not require comprehensive or collision, but most lenders and leasing companies do while there is a loan or lease balance. If the required insurance lapses, the lender can impose “forced coverage,” which is typically more expensive and offers limited protection.
Oak Creek residents who just bought or leased a vehicle from a Milwaukee-area dealership should contact the agency promptly so their coverage lines up with lender expectations before driving off the lot.
SR-22 Auto Insurance Help for Oak Creek Drivers
Some Oak Creek drivers need to file proof of insurance with the Wisconsin DMV after certain suspensions or revocations. This process involves an SR-22 certificate, which is often misunderstood. An SR-22 is a certificate the insurer files with the Wisconsin DMV. It is not an insurance policy itself. For detailed guidance, read the SR-22 insurance page.
How an SR-22 Works in Wisconsin
The SR-22 proves you carry at least the minimum required liability coverage. Your insurer files it electronically or by mail with the DMV. The Wisconsin DOT proof of insurance page details the official requirements, including what the SR-22 form must contain: insured’s name, policy number, effective dates, owner/operator designation, Wisconsin listed as the state, insurer name, and an authorized signature.
How long the SR-22 must stay on file is determined by the DMV, not by the insurance agency. In many cases, the filing period is three years from the date you become eligible to reinstate driving privileges. Canceling or lapsing the SR-22 policy while the filing is still required can trigger another suspension.
Getting an SR-22 Policy Quote from Oak Creek
Oak Creek drivers can request an SR-22-friendly quote through the SR-22 page or by calling (844) 317-1313. Information typically needed includes driver license details, record of recent tickets or OWI, vehicle year and make, and whether you need owner or non-owner coverage.
Eligibility and pricing depend on the insurer’s underwriting. The agency cannot guarantee approval or a specific rate.
Non-Owner Auto Insurance and Non-Owner SR-22 in Oak Creek
Some Oak Creek residents need proof of insurance to reinstate a license but do not currently own a vehicle. A non-owner policy can address this. Learn more on the non-owner SR-22 page.
What Non-Owner Auto Insurance Covers
Non-owner policies generally provide liability coverage when driving vehicles you do not own, such as borrowed cars or occasional rentals. They usually do not include collision or comprehensive for vehicle damage and typically exclude vehicles you have regular access to or that are registered in your household.
Wisconsin non-owner auto policies include required UM bodily injury coverage; eligibility and policy forms depend on the insurer.
When Oak Creek Drivers Consider Non-Owner SR-22
Common situations: your license was suspended for certain violations, you do not currently own a car, and you occasionally borrow or rent a vehicle. Regular access to a household or employer vehicle can affect eligibility; tell the agent about that access before applying.
The DMV controls SR-22 duration and reinstatement fees. An agent can explain the insurance side but cannot change DMV requirements or timelines.
Our Oak Creek Auto Insurance Services
Below is a summary of the main ways WisconsinAutoInsurance.com helps Oak Creek drivers find and understand coverage.
Standard Auto Insurance for Cars, SUVs, and Pickups
The agency helps Oak Creek residents insure daily-use vehicles for commuting, school runs, and errands around Drexel Town Square and Lake Vista Park. Policies can include liability, UM, MedPay, and optional physical damage coverages depending on driver needs and insurer offerings. Drivers can compare auto insurance options through WisconsinAutoInsurance.com to find a policy that fits their situation.
Coverage for Drivers with Tickets, Accidents, or Lapses
The agency regularly speaks with Oak Creek drivers who have recent speeding tickets on I-94, minor at-fault accidents, or periods without insurance. Not every driver will qualify with every insurer. As an independent agency, the team can explore options with multiple companies. Drivers should compare auto insurance quotes based on identical coverage limits and deductibles to make meaningful comparisons.
Help for New Wisconsin Drivers and New Oak Creek Residents
People moving into Oak Creek from another state need a Wisconsin-compliant policy and help understanding state minimums, which differ from most neighboring states. New drivers or recent graduates getting a first policy also benefit from a walkthrough of required versus optional coverages. Use OCI consumer resources to understand insurance rules; confirm your specific coverage with the agent or insurer.
How Our Oak Creek Auto Insurance Quote Process Works
Getting started is straightforward and happens entirely by phone or online, whether you are in Oak Creek, Milwaukee, or a nearby community.
Step 1: Share Your Oak Creek Driving Details
Complete the online quote form or call (844) 317-1313. The main information needed: your Oak Creek address where the car is garaged, vehicle year/make/model, how the vehicle is used (commuting, pleasure, business), driver license history, and any lender or lease requirements.
Providing accurate information helps avoid surprises later in underwriting. If you have household members with separate licenses, mention them upfront.
Step 2: We Compare Wisconsin Policy Options
The agency reviews options from the insurers it works with. The review covers liability limits, UM/UIM, physical damage coverages, deductibles, and available payment options to match your goals. Individual rates depend on driving record, vehicle type, garaging location, selected coverages and other underwriting factors.
The agent walks through differences in plain language so you understand trade-offs before choosing.
Step 3: You Choose Coverage and Confirm Your Policy
Once you select a quote, the agent helps complete the application and any required signatures electronically or by phone. Coverage begins at the effective date and time confirmed by an authorized agent or insurer, subject to binding and payment requirements. Requesting a quote alone does not start coverage.
For SR-22 cases, the insurer typically files the SR-22 with the Wisconsin DMV after the policy is active, with timing based on the insurer’s procedures.
Results and Peace of Mind for Oak Creek Drivers
The goal is straightforward: Oak Creek drivers finish the process understanding what their policy covers and what it does not, with limits that fit their budget and risk comfort. When life changes (new car, move, added teen driver, ticket), having a Wisconsin-focused agency available by phone means answers are accessible without scheduling an in-person visit.
Understanding claims concepts like deductibles, actual cash value, total loss thresholds, and Wisconsin’s comparative negligence rules before a loss happens makes the claims process less stressful. An agent can help explain the claims process, but the insurer determines coverage and payment under the policy.
Oak Creek and Nearby Areas We Serve
While the agency operates remotely, Oak Creek and the greater Milwaukee region are a primary focus. Local points of reference include neighborhoods around Drexel Town Square, Lake Vista Park, areas near South Howell Avenue and Ryan Road.
The agency also helps drivers throughout Milwaukee County and nearby Racine County communities. Visit the cities hub page to see other Wisconsin locations served. All service is by phone and online; there is no public walk-in office in Oak Creek or elsewhere.
Helpful Auto Insurance Resources for Oak Creek Drivers
These links collect reliable, official sources for further reading on Wisconsin auto insurance and driving rules.
WisconsinAutoInsurance.com resources:
-
Minimum car insurance in Wisconsin for a detailed look at state minimums and why many drivers choose higher limits.
-
SR-22 insurance for more about proof of insurance filings.
-
Non-owner SR-22 for drivers needing SR-22 without owning a car.
-
Cities we serve for other Wisconsin city-specific pages.
Official government resources:
-
Milwaukee County and Oak Creek police and fire resources are available through official city and county websites.
Frequently Asked Questions About Oak Creek Auto Insurance
These FAQs answer common questions Oak Creek drivers ask before requesting a quote or changing coverage.
How much auto insurance do I legally need in Oak Creek, Wisconsin?
Oak Creek drivers follow Wisconsin law: at least 25/50/10 liability ($25,000 bodily injury per person, $50,000 per accident, $10,000 property damage) and 25/50 uninsured motorist bodily injury. Insurers must offer at least $1,000 in MedPay, which you can decline. Lenders may require additional coverage like comprehensive and collision for financed or leased vehicles; the state does not.
Does WisconsinAutoInsurance.com offer the “cheapest” auto insurance in Oak Creek?
No agency can guarantee the lowest rate. As an independent agency, WisconsinAutoInsurance.com helps you compare options from multiple insurers. Rates depend on each insurer’s underwriting and your specific driving profile. The focus is on both cost and adequate protection, not price alone.
Can I get coverage today if I need to drive to work in Oak Creek?
Some policies can start quickly once underwriting is complete and payment is arranged. Timing varies by insurer and circumstance. A quote request by itself does not activate coverage; confirm binding and the effective date and time with the authorized agent or insurer.
What if I had a lapse in coverage while living in Oak Creek?
A coverage lapse means a period when you had no active auto insurance. Lapses can affect pricing and underwriting because insurers view continuous coverage as a positive risk factor. The agency can still explore options for many drivers with lapses but cannot promise acceptance by any specific insurer.
Does auto insurance cover my personal items if my car is broken into in Oak Creek?
Comprehensive coverage typically covers damage to the vehicle itself in a covered theft-related loss, subject to your deductible and policy terms. Stolen personal belongings, like laptops or tools, are usually not covered under auto policies. Those items may fall under homeowners insurance or renters insurance, depending on those separate policies.
Who is covered to drive my car in Oak Creek?
Auto policies usually extend coverage to household members and sometimes permissive drivers, but rules vary by insurer and policy language. Tell your agent about all regular household drivers so the policy can be set up correctly and you do not face a coverage dispute at claim time.
How do claims work if I’m in a crash on I-94 or Howell Avenue?
Report the claim to your insurer as soon as possible. Cooperate with the adjuster’s investigation. Your deductible applies to physical damage claims on your own vehicle. Wisconsin uses comparative negligence rules, which means fault and payments can be shared between drivers based on each party’s role in the crash. The OCI consumer guide explains how this works in detail.
Get Started with Oak Creek Auto Insurance
Whether you commute on I-94, protect a family fleet, or need to reinstate your license with an SR-22, WisconsinAutoInsurance.com provides Wisconsin-specific guidance and quotes tailored to Oak Creek drivers.
Request a quote online or call (844) 317-1313 during business hours to talk with a licensed Wisconsin agent.
WisconsinAutoInsurance.com · Drivers Insurance Agency, Inc. · Serving Oak Creek and Wisconsin drivers by phone and online (no public walk-in office).