On this page
Green Bay Auto Insurance for Everyday Driving on I‑41, I‑43, and Downtown Streets
If you drive in Green Bay, your insurance needs are shaped by the roads you actually use: merging onto I‑41 toward Appleton, crossing the Fox River on WIS 172, or squeezing into a downtown parking spot near the river on a February night. The right coverage depends on those daily patterns, not on a generic statewide template.
WisconsinAutoInsurance.com (Drivers Insurance Agency, Inc.) is an independent insurance agency that helps Green Bay households compare Wisconsin auto insurance options by phone and online. Whether you have a clean record or need to navigate tickets, accidents, or a coverage gap, the team can walk through your situation and explain what fits your budget and driving life.
Call (844) 317-1313 or request a quote online to start. A quote request does not bind coverage; it simply opens a conversation about your options.
Why Green Bay Drivers Choose WisconsinAutoInsurance.com
Green Bay families want coverage advice grounded in local driving conditions, not a sales pitch. WisconsinAutoInsurance.com is Drivers Insurance Agency, Inc., serving Green Bay and surrounding communities across Wisconsin by phone and online. The agency focuses on personalized service through phone conversations and its website.
What Sets Our Green Bay Auto Insurance Help Apart
-
Independent agency access: As an independent agency, we can compare insurance plans from multiple insurance carriers rather than representing a single insurance company. Independent agencies offer multiple insurance options, giving clients a broader view of what is available.
-
Phone and online service: Green Bay households can reach us at (844) 317-1313 or through our quote page without needing to visit an office.
-
Plain‑language coverage explanations: We walk through Wisconsin coverages (liability, uninsured motorist, collision, comprehensive, SR‑22, non‑owner when available) so you understand what each one does and does not cover before you choose.
-
Coverage matched to local conditions: Selecting sensible deductibles for winter claims, aligning coverage with lender requirements on a financed vehicle, and making sure you are not caught off guard after a crash on I‑43 are the kinds of decisions we help Green Bay drivers work through.
Required Auto Insurance in Green Bay, WI
Wisconsin law sets the floor for auto insurance coverage. The Wisconsin Office of the Commissioner of Insurance publishes the official consumer guide to these requirements, and the same statewide requirements apply in Green Bay. Most drivers meet Wisconsin’s financial-responsibility requirements through liability insurance; limited statutory alternatives exist.
Wisconsin Liability Minimums: 25/50/10
Wisconsin requires minimum liability coverage of $25,000 per person and $50,000 per accident for bodily injury, plus $10,000 per accident for property damage. Liability insurance covers damages to others in an accident; it pays for another person’s medical expenses, lost wages, and property repair when you are at fault. It does not cover your own injuries or your vehicle.
Picture a rear‑end collision on I‑41 during a slowdown near the De Pere exit. If you caused it, your liability coverage responds to the other driver’s medical bills and vehicle repair. With only $25,000 per person in bodily injury coverage, a single hospital stay could exceed that limit and leave you personally responsible for the rest.
Many Green Bay households choose higher limits to protect their income and assets. For more on how state minimums work, see our Minimum Car Insurance page.
Required Uninsured Motorist (UM) in Wisconsin
Wisconsin also requires uninsured motorist bodily injury coverage at 25/50 limits. Uninsured motorist coverage is essential for financial protection; it helps pay for injuries to you and your passengers when the at‑fault driver has no liability insurance, including qualifying hit-and-run claims subject to policy and legal requirements.
UM does not pay for damage to your vehicle. If an uninsured driver runs a red light at a Fox River bridge intersection and hits your car, UM may cover eligible injury damages up to your limits. Vehicle repairs may fall under collision coverage, subject to its deductible and terms, or be your responsibility.
Optional Underinsured Motorist (UIM) and Med Pay
UIM coverage is optional in Wisconsin. Insurers must offer it, but you can decline. If purchased, minimum UIM limits are $50,000 per person and $100,000 per accident. UIM can help when the at‑fault driver’s liability limit is lower than your UIM limit, subject to offsets and specific policy terms.
Medical Payments (Med Pay) coverage must also be offered but can be declined. If accepted, the minimum limit is $1,000 per person. Med Pay can help cover eligible medical or funeral expenses after an accident regardless of fault. Ask how it coordinates with your health insurance and which policy pays first. A winter slide‑off on WIS 172 that sends you to a Green Bay emergency room could generate bills that Med Pay helps address while your health plan processes its portion.
Key Green Bay Coverage Decisions: Beyond the Minimum
State minimums keep you legal. The coverage decisions that actually protect your household go further, and they connect directly to how you use your vehicle in and around Green Bay.
Comprehensive vs. Collision Coverage
Collision coverage pays for damage to your vehicle when you hit another car or object, minus your deductible. Comprehensive coverage protects against non‑collision incidents: theft, vandalism, fire, hail, falling trees, or hitting a deer.
Drivers traveling beyond Green Bay may encounter deer, while parked vehicles can be exposed to hail, wind, theft, or vandalism. Comprehensive and collision address different causes of physical damage, subject to policy terms. Lenders typically require both for financed or leased vehicles. If your car is paid off and its market value is low, you have more flexibility; you may adjust or drop physical damage coverage after weighing the vehicle’s value against the cost of the coverage.
Choosing Deductibles in a Green Bay Winter
Green Bay winters bring snow, ice, and freezing temperatures. Minor fender‑benders in icy parking lots, contact with hidden curbs under snowbanks, and spin‑outs on WIS 172 are not rare events. Raising your comprehensive and collision deductibles from $500 to $1,000 can reduce monthly premiums, but it also means more out-of-pocket cost on a covered claim to which that deductible applies. Consider your emergency savings and likely repair costs before raising deductibles.
Optional Coverages Green Bay Households Often Consider
-
Roadside assistance and towing: A slide‑off on I‑43 during a January storm can leave you waiting for hours. Towing coverage may help with an eligible tow, subject to distance, dollar, and service limits.
-
Rental reimbursement: If your vehicle is in a Green Bay body shop for a week after a collision, rental reimbursement may help pay for a rental after a covered loss, subject to daily and total limits.
-
Loan/lease gap coverage: If your financed vehicle is totaled, gap coverage can help pay the difference between the insurance payout and your remaining loan balance.
Availability varies by insurer and underwriting. Not every option is available to every driver.

How Green Bay Driving Conditions Affect Coverage Choices
Where and how you drive in Green Bay can influence which coverages feel most important. The Wisconsin DOT Green Bay highway map shows the network of interstates and state routes that shape daily travel here.
Highways: I‑41, I‑43, and WIS 172
I‑41 connects Green Bay to Appleton and Oshkosh. I‑43 runs south from Green Bay toward Manitowoc. WIS 172 serves as a southern bypass, connecting communities on both sides of the Fox River. Truck traffic, higher speeds, and multi‑vehicle collisions are regular risks on these corridors. That exposure is a practical reason to consider liability limits above the 25/50/10 floor and to carry collision coverage.
If you commute between Green Bay and Appleton or Oshkosh, our Appleton Auto Insurance and Oshkosh Auto Insurance pages cover local conditions along those routes.
Fox River Crossings and Downtown Green Bay Parking
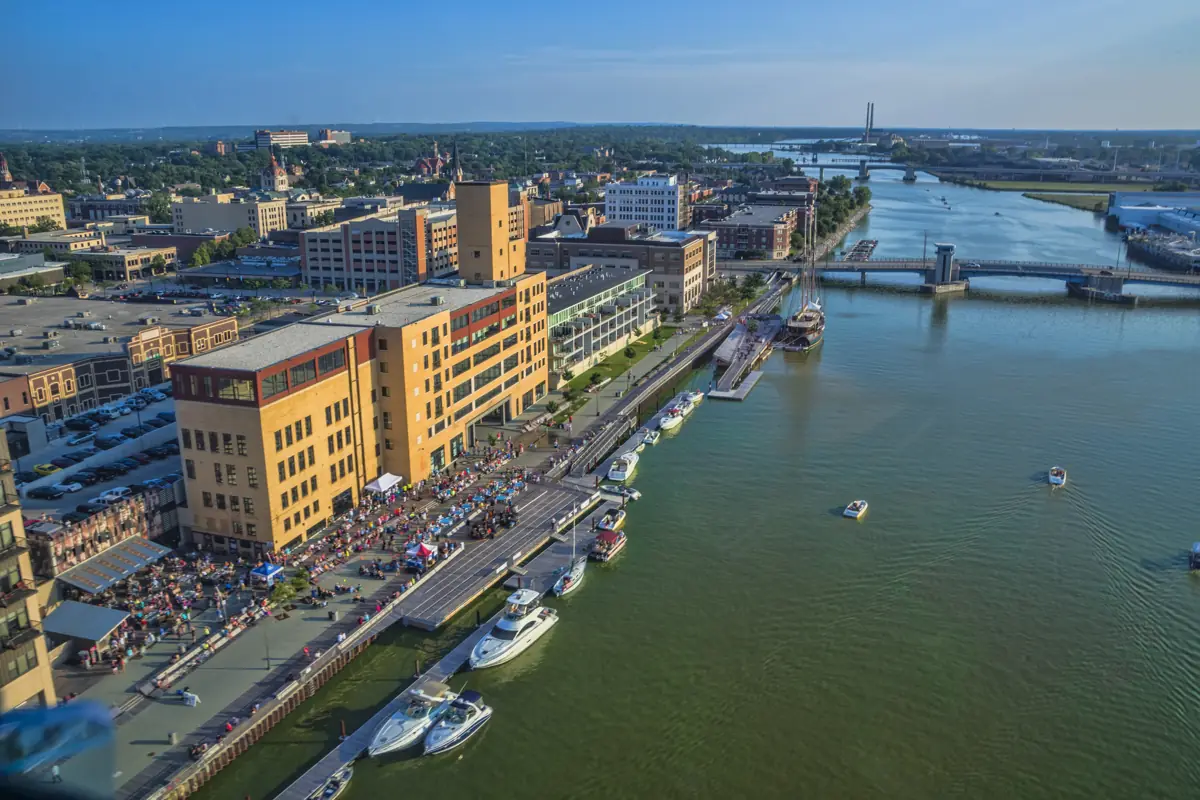
The Ray Nitschke Memorial Bridge connects downtown streets across the Fox River. Congestion near downtown business districts and events increases rear‑end collision risk at bridge approaches. Many Green Bay residents rely on street or surface‑lot parking near downtown apartments and the riverfront. Check the City of Green Bay night‑parking page for current overnight parking rules: overnight restrictions, permission requirements, and snow-emergency rules can affect where you may park. Parked‑car damage, hit‑and‑run incidents, and break‑ins are realities of street parking; comprehensive and collision coverage respond to those losses, subject to your deductible and policy terms.
Snow Emergencies and Winter Streets
Snow and ice increase spin‑outs, rear‑end collisions, and damage from plowing operations. The City of Green Bay snow‑emergency page posts current procedures for parking and plowing. Maintaining coverage year‑round, rather than dropping it during months you drive less, keeps you legal and protected when conditions are worst.
Hypothetical Green Bay Auto Insurance Scenarios
The following examples illustrate how different coverages can work together. They are not quotes, promises of eligibility, or claims outcomes.
Scenario 1: Daily Commuter on I‑41
A driver commutes from Green Bay to Appleton in a financed SUV, logging highway miles five days a week. Their lender requires collision and comprehensive. They carry liability above 25/50/10, UM at state minimums, and add UIM and roadside assistance. WisconsinAutoInsurance.com compares coverage options from multiple insurers so this driver can see how different liability limits and deductibles affect what they pay.
Scenario 2: Street‑Parked Car Near Downtown Green Bay
A household parks their sedan on the street near the Fox River. Night‑parking rules, snow‑emergency moves, and the risk of parked‑car hits or break‑ins are constant concerns. In this hypothetical example, the household chooses a $500 deductible for each physical-damage coverage and sets aside savings for an eligible claim. Actual deductibles and claim payments depend on the policy. Comparing quotes helps find tailored coverage for specific needs like this.
Scenario 3: Paid‑Off Vehicle Used Mostly Around Town
An older, paid‑off hatchback handles errands within Green Bay and nearby suburbs. No lender requires physical damage coverage. The owner weighs the car’s market value against the annual cost of comprehensive and collision. The owner also considers the deductible and whether replacing the car without an insurance payment would be affordable. The agency walks through the pros and cons without pushing a one‑size‑fits‑all answer.
SR‑22 and Non‑Owner Coverage for Green Bay Drivers
Some Green Bay residents contact us after a license suspension or an insurance problem. Understanding SR‑22 and non‑owner coverage options is the first step.
When a Wisconsin SR‑22 May Be Required
An SR‑22 is a certificate your insurance company files with the Wisconsin DMV to confirm you carry at least the state’s minimum liability limits. Insurers offering Wisconsin SR‑22 filings may help eligible drivers meet a DMV reinstatement requirement. It is not a separate type of policy. SR‑22 filings are required only in specific DMV situations, such as certain convictions or license suspensions; not every driver with a lapse or violation needs one. Your DMV or court documents will state whether an SR‑22 is required and for how long (three years from eligibility for reinstatement in applicable revocation cases; other situations differ). Visit our SR‑22 Insurance page for details.
Non‑Owner SR‑22 and Non‑Owner Policies
Non‑owner auto insurance provides liability coverage for a person who does not own a vehicle and does not have regular access to a household car. Some Green Bay residents need a non‑owner SR‑22 to reinstate driving privileges when they do not own a car. Non‑owner policies insure the person, not a specific vehicle, and do not include collision or comprehensive coverage. Not all insurers offer non‑owner coverage; eligibility and pricing depend on underwriting. See our Non‑Owner SR‑22 page for more detail.
How Our Green Bay Auto Insurance Quote Process Works
Getting started takes a few minutes by phone or online. Coverage is not active until properly bound by the insurer or an authorized agent.
Step 1: Share Your Green Bay Driving Picture
Call (844) 317-1313 or use our quote form. We ask about your vehicles, drivers, driving history, and how you use your cars in and around Green Bay. The conversation focuses on coverage needs, not pressure to buy.
Step 2: Compare Wisconsin Auto Insurance Options
We review available insurance products from multiple insurers and explain differences in liability limits, deductibles, and optional coverages as they relate to your driving patterns. Insurance quotes vary based on age, vehicle, driving history, and location. All offers depend on insurer underwriting; eligibility is not guaranteed.
Step 3: Choose Coverage and Confirm Your Start Date
If you decide to move forward, we review selected coverages and the effective date and time before requesting to bind coverage with the insurer. Coverage begins at the confirmed effective date and time after the insurer or authorized agent binds the policy. Do not cancel existing coverage until your new policy is confirmed active.
How We Serve Green Bay and Nearby Communities
Many households around Green Bay commute, shop, or attend events across Northeast Wisconsin. We serve the City of Green Bay, De Pere, Ashwaubenon, Bellevue, Howard, Suamico, Allouez, and surrounding Brown County communities. Visit our Cities page for other Wisconsin locations.
Getting Ready for Your Green Bay Auto Insurance Quote
A few minutes of preparation makes the quote conversation faster.
Quote Preparation Checklist
-
Driver information: Full names, dates of birth, license numbers if available, estimated annual miles (including highway vs. city driving in Green Bay).
-
Vehicle information: Year, make, model, VIN if accessible, and whether each vehicle is financed, leased, or paid off.
-
Driving history: Recent tickets, accidents, or suspensions with approximate dates.
-
Current coverage snapshot: Existing liability limits, deductibles, and any optional coverages you want to keep or change.
-
Household goals: Lowering risk exposure, adjusting deductibles for winter, meeting lender requirements, adding a newly licensed driver. Compare eligible household-policy options and ask whether a good-student discount is available; pricing and eligibility vary.
Frequently Asked Questions About Green Bay Auto Insurance
How much auto insurance do I really need in Green Bay?
Wisconsin requires at least 25/50/10 liability and 25/50 UM. Many households choose higher limits to protect income and assets. Green Bay’s highway traffic, winter roads, and parking conditions can influence how comfortable you feel at those minimums. An agent can lay out a few liability and deductible combinations side by side so you can see the trade‑offs.
Do winter roads in Green Bay automatically make my insurance cost more?
Insurers consider driving record, vehicle type, garaging address, and coverage choices together. No single street or neighborhood guarantees a higher premium. Your actual quote is more useful than a citywide or national average without matching driver and coverage assumptions. Winter conditions tend to influence which coverages you prioritize (collision, comprehensive, towing) rather than dictating a specific price. Maintaining a clean credit record can help lower insurance rates over time in Wisconsin.
Is state minimum coverage enough if I mostly drive around town?
State minimums satisfy legal requirements but can be exceeded quickly. A serious intersection crash can exceed the bodily-injury or property-damage limits of a minimum policy. The $25,000 per-person limit applies to bodily injury, while property damage has a separate $10,000 minimum limit. Consider higher limits and review your options with an agent.
Can I get auto insurance in Green Bay if I’ve had a lapse or tickets?
Some insurers offer coverage after tickets, accidents, or a lapse, subject to underwriting. An SR‑22 is required only when the Wisconsin DMV mandates it; not every driver with a violation needs one. We can help explore options but cannot guarantee eligibility or a specific rate.
How can I look for more affordable coverage without cutting important protection?
Adjusting deductibles, reviewing optional coverages, bundling policies, and asking about available discounts are practical starting points. Ask about eligible bundling discounts and compare the combined cost. Telematics programs use driving data; review privacy terms and whether driving results can increase as well as decrease the premium. A policy review can reveal coverage differences, but savings are not guaranteed. See our Cheap Car Insurance page for broader guidance on seeking value in Wisconsin auto coverage.
Green Bay Driver Resources
For local reporting and safety information, use the Green Bay Police Department and Green Bay Metro Fire Department. Call 911 for an emergency. For license and registration services, check the Green Bay DMV service center at 942 Vanderperren Way for current services, hours, and appointment requirements before visiting. These government resources are separate from our agency.
Request Your Green Bay Auto Insurance Quote
WisconsinAutoInsurance.com helps Green Bay drivers match coverage to the roads they actually drive: I‑41 and I‑43 commutes, Fox River crossings, downtown parking, and Brown County winter weather. Coverage choices are personal, and an independent agent can explain liability limits, UM/UIM, Med Pay, and physical damage coverage clearly so you can decide with confidence.
Call (844) 317-1313 or start your quote online today to compare Wisconsin auto insurance options for your Green Bay household. Coverage begins only after the insurer or authorized agent confirms that a policy is bound with an effective date and time.