On this page
Wausau WI Auto Insurance for Everyday Drivers
Whether you commute on US-51 near Wausau or connect to I-39 farther south, drive Highway 29 between Weston and Rothschild, or navigate rural Marathon County roads at dusk hoping to avoid a deer, finding the right auto insurance matters. Wausau drivers face a specific mix of winter weather, highway congestion, wildlife, and city parking challenges – and coverage should reflect those realities, not a generic template from somewhere else.
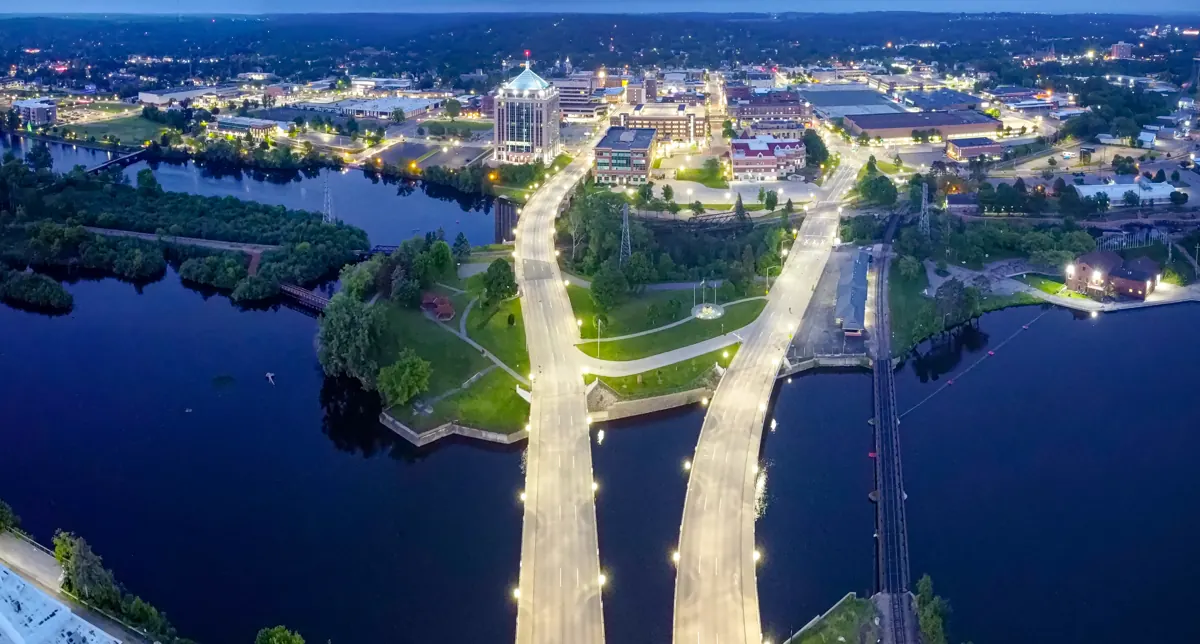

Common reasons Wausau residents start looking for auto insurance include buying a vehicle from a local dealer, adding a teen driver attending Wausau West or D.C. Everest, dealing with a speeding ticket on US-51, filing a comprehensive claim after a deer strike on a county highway, or needing an SR-22 certificate after a DMV suspension. Whatever your situation, WisconsinAutoInsurance.com – operated by Drivers Insurance Agency, Inc. – helps Wausau and Marathon County drivers compare Wisconsin auto insurance coverage options by phone and online with remote support for drivers across Wausau and Marathon County.
Call (844) 317-1313 or request a quote online to start reviewing your options. Requesting a quote does not bind you to coverage.
Throughout this page, coverage explanations are specific to Wisconsin law – including the required 25/50/10 liability minimums, mandatory uninsured motorist bodily injury coverage, and optional protections – and grounded in the driving realities of Wausau, WI.
Why Wausau Drivers Turn to WisconsinAutoInsurance.com
Local knowledge of Wausau roads, north-central Wisconsin seasons, and state DMV rules helps drivers choose coverage that actually fits their daily life. As an independent agency not tied to one insurance company, WisconsinAutoInsurance.com focuses exclusively on Wisconsin drivers and can access multiple carriers to help you find a policy designed for your needs.
Local Experience for Wausau and Marathon County
-
Familiar with Wausau commuting patterns: Wisconsin River bridge crossings, downtown congestion on Grand Avenue and Bridge Street, I-39/US-51 traffic flow, Highway 29 east-west corridors, and trips out to Rib Mountain and surrounding rural areas.
-
Guidance tailored to issues common in north-central Wisconsin – deer and wildlife collisions on county highways, winter driving on icy roads, and the mix of city streets and rural routes that define life in Marathon County.
-
Independent agencies can compare participating insurers, giving you more coverage options to compare rather than being limited to a single carrier’s products.
-
Phone and online service across Marathon County and all of Wisconsin – no walk-in office, but direct access to agents who understand local conditions.
Clear, Pressure-Free Coverage Explanations
The agency takes time to walk through each coverage type – liability, uninsured motorist, comprehensive, collision, MedPay, and optional underinsured motorist – to advise, not just sell a policy, so Wausau households can decide what fits their budget and risk comfort. There are no guarantees of the “lowest rate,” but there is a focus on helping you understand trade-offs and compare available options with confidence.
Help is available whether you have a clean driving record, recent tickets, at-fault accidents, a coverage lapse, or need SR-22 insurance or non-owner coverage.
Remote Convenience for Busy Wausau Schedules
Quotes and policy changes can typically be started by phone or online, without needing to visit an office. This works well for people balancing work at local employers, Northcentral Technical College classes, or family obligations around school and activities. Online service tools help you save time when managing insurance quotes and policy changes on your time, not ours.
Call (844) 317-1313 or start at the quote page to get moving.
Wausau Auto Insurance Coverage Options
Rush-hour fender benders downtown, an icy bridge accident over the Wisconsin River, a deer hit on a county highway, hail damage during a July storm – each of these situations involves a different type of coverage. Wisconsin has specific minimum requirements, but many drivers choose higher limits or extra protections, especially when driving newer vehicles or carrying a loan.
Wisconsin Liability Insurance Requirements (25/50/10)
Wisconsin requires a minimum of $25,000 liability coverage per person for bodily injury, $50,000 per accident for bodily injury, and $10,000 for property damage. Bodily injury liability limits in Wisconsin are set at 25,000 per person and 50,000 per accident. These minimums apply to most registered vehicles in the state.
In plain language, liability coverage pays for damages to others’ property and injuries to other people when you cause a crash – for example, rear-ending another car on Grand Avenue or causing a multi-vehicle collision merging onto I-39. Liability does not pay for your own vehicle’s damage or your own injuries.
Many Wausau households consider higher liability limits like 100/300/100 to protect personal assets – wages, savings, and homes – in case a serious crash results in claims that exceed the minimums. Ask for quotes at different limits to evaluate the cost difference for your household.
For a deeper look at what Wisconsin law requires, visit the Minimum Car Insurance Wisconsin page.
Uninsured Motorist (UM) and Optional Underinsured Motorist (UIM)
Drivers must carry uninsured motorist coverage in Wisconsin, with bodily injury limits of at least $25,000 per person and $50,000 per accident. Uninsured motorist coverage protects against uninsured drivers – it covers you and your passengers for injuries if you’re hit by a driver who carries no insurance or in a hit-and-run situation.
An important distinction: UM in Wisconsin does not pay for vehicle damage or losses from deer strikes or weather events. It covers bodily injury only.
Underinsured motorist (UIM) coverage is optional, but if you choose to add it, Wisconsin law requires limits of at least $50,000 per person and $100,000 per accident. UIM can help when an at-fault driver’s liability limits are too low to cover your medical costs – for example, after a serious injury crash on US-51 or Highway 29 where hospital bills, surgery, and rehabilitation quickly exceed the other driver’s policy limits. Limits, offsets and the policy definition of underinsured affect payment; the benefit is not automatically the difference between two coverage limits.
Collision Coverage for Crashes
Collision coverage pays for your vehicle’s damages after an accident – specifically when your car collides with another vehicle or object, or overturns, minus your chosen deductible.
Local examples where collision coverage applies: sliding into a guardrail on an icy bridge over the Wisconsin River, backing into a concrete pole in a Wausau parking ramp, or a chain-reaction crash at a busy I-39 exit during rush hour. Even if you’re at fault, collision coverage responds to repair or replace your vehicle up to its actual cash value.
Collision is not required by Wisconsin law, but lenders and lessors typically require it for financed or leased vehicles. Choosing a higher deductible (say $1,000 instead of $500) reduces your premium but increases what you pay out of pocket each time you file a claim. An agent can help you weigh that trade-off based on your situation.
Comprehensive Coverage for Deer, Weather, and Non-Crash Damage
Comprehensive coverage protects against non-collision incidents – events like animal strikes (including deer), hail, falling objects, fire, theft, vandalism, and certain types of glass damage, subject to your policy terms and deductible. Review comprehensive for direct animal strikes and covered weather damage, and collision for skidding into another vehicle or object.
A critical distinction many drivers miss: hitting a deer is usually a comprehensive claim. But if you swerve to miss a deer and strike a tree or another car, that’s typically a collision claim – a different coverage with potentially a different deductible.
Stolen personal belongings taken from inside your car are generally not covered by auto comprehensive coverage. Those losses may fall under a homeowners or renters policy, depending on circumstances.
In Wausau, comprehensive coverage is particularly relevant for rural commutes in Marathon County, parking near Rib Mountain shopping areas where hail or falling branches can cause damage, and the ever-present risk of deer on wooded county roads at dawn and dusk. Lenders commonly require both collision and comprehensive when a vehicle is financed or leased.
Medical Payments (MedPay) Coverage
Wisconsin insurers must offer MedPay coverage of at least $1,000 per person if elected, but drivers may decline it. Wisconsin does not mandate personal injury protection (PIP) coverage, making MedPay the primary optional medical coverage on a standard auto policy.
MedPay can help pay medical bills for you and your passengers after a crash, regardless of who was at fault, up to your chosen limit. Common uses in Wausau include emergency room visits after a winter crash on an icy road or treatment for minor injuries from a neighborhood fender bender. For family members who ride with you regularly, MedPay provides an extra layer of protection beyond what health insurance alone may cover.
Other Personal Insurance Coverage Options Often Requested in Wausau
Beyond the core coverages, some insurers offer add-ons that Wausau drivers frequently ask about:
-
Roadside assistance – Drivers should evaluate additional options like roadside assistance in their insurance policies, especially useful when stranded on I-39 during a snowstorm or dealing with a flat tire on a rural county road.
-
Rental reimbursement (loss of use) – Helps cover the cost of a rental car while your vehicle is in a Wausau body shop after a covered claim.
-
Loan/lease gap coverage – Pays the difference between your vehicle’s actual cash value and what you still owe on a loan or lease if the car is totaled.
Availability of these options varies by insurer. An agent can help you understand what’s offered and whether it fits your budget and driving patterns.
Getting a Wausau Auto Insurance Quote with WisconsinAutoInsurance.com
Starting a quote takes minutes by phone or online. Many Wausau drivers call on a break at work or from home in the evening. The agency provides quotes and helps you compare – but coverage begins at the effective date and time confirmed by an authorized agent or insurer, subject to binding and payment requirements.
Step 1: Reach Out for Your Wausau Auto Insurance Quote
Call (844) 317-1313 or visit the quote page to begin. Before you contact us, gather:
-
Driver’s license numbers for all household drivers
-
Vehicle identification numbers (VINs) for each vehicle
-
Your garaging address in Wausau or nearby communities
-
Current insurer name, policy number, and coverage limits (if any)
The agency can assist drivers in many situations: new teen drivers, a recent move to Wausau, changing vehicles at a local dealership, or needing proof of insurance for a lender. Comparing auto insurance quotes requires matching the same coverage types and limits across options – your agent will help ensure you’re making apples-to-apples comparisons.
Step 2: Review Wisconsin Coverages and Options Together
An agent walks through liability limits, UM, optional UIM, MedPay, comprehensive, collision, deductibles, and possible endorsements. The conversation includes how your car is actually used – commuting to local employers, weekend trips to Green Bay or Appleton, longer drives across Wisconsin – and how usage may influence coverage choices.
No single coverage recommendation fits everyone. The goal is to help you understand your choices and build the combination that fits your family’s situation, budget, and comfort level. Mention other policies you hold so the agent can check eligible multi-policy discounts and compare total costs.
Step 3: Decide, Bind a Policy, and Get Proof of Insurance
Once you choose an option, the agency can help submit the application. Once the insurer issues the policy, proof of insurance is typically provided via email or app, subject to insurer processes. Some insurers may also provide a link to access policy documents or claim-related account tools, depending on carrier processes. A quote itself does not bind coverage – confirm binding and the effective date and time before relying on protection.
Typical uses for proof of insurance: meeting applicable DMV instructions, satisfying a lender’s requirements, or keeping ID cards in the glove box for Wausau Police traffic stops or minor accidents.
Help for Wausau Drivers with Tickets, Accidents, or Lapses
Many Wausau drivers look for coverage after difficult events – speeding tickets on US-51, an OWI charge, at-fault crashes on icy roads, or a lapse after a policy cancelled for non-payment. The agency cannot promise eligibility or specific rates, but can often help explore options for higher-risk situations where finding personal insurance feels harder.
SR-22 Filings for Wisconsin DMV
An SR-22 is required for certain drivers under Wisconsin DMV rules – but it is a certificate of financial responsibility filed with the DMV, not an insurance policy by itself. Drivers may need an SR-22 after certain suspensions, OWI convictions, uninsured crashes, or damage judgments. The Wisconsin DOT proof-of-insurance page outlines when an SR-22 is required and how filings work.
Most insurers licensed in Wisconsin file the SR-22 electronically, and the record typically appears on the driver’s DMV record within one to two business days once a qualifying policy is in place. The policy providing the SR-22 must remain active for the full DMV-required period. Canceling before that period ends can lead to another suspension.
An occupational license (restricted driving privileges) following a suspension often requires having an SR-22 on file. In rare cases, Wisconsin law allows alternatives such as a surety bond or cash deposit with the DMV in lieu of insurance.
For more detail, visit the SR-22 Insurance page.
Non-Owner Auto Insurance and Non-Owner SR-22
Non-owner auto insurance is coverage for drivers who do not own a vehicle and do not have regular access to one but still need liability and required UM coverage when they occasionally drive cars they do not own. These policies generally do not include collision or comprehensive coverage for any vehicle. A non-owner policy may include SR-22 filings if needed, depending on eligibility.
Eligibility typically depends on not owning a vehicle and not having regular access to a household car in Wausau. These policies are not for vehicles titled in the driver’s name.
Learn more on the Non-Owner SR-22 page.
Coverage After a Lapse or Cancellation
Some Wausau drivers come back to the market after a policy ended for non-payment or after going without insurance for months or years. Companies may review driving history, claims, lapses, and credit information (where allowed under Wisconsin OCI guidance) when deciding how to rate or whether to offer a policy. Insurers cannot use credit information as the sole basis to refuse, cancel, or nonrenew a policy – but it can be a factor.
The agency can still review available options, though there are no guarantees of approval or pricing. Even short lapses can affect future rates and may complicate SR-22 requirements.
How Much Auto Insurance Do Wausau Drivers Need?
Wisconsin’s minimums provide a legal floor, but they may not be enough for many households. Medical costs from a serious crash can exceed $25,000 per person quickly, and vehicle values have risen. The question isn’t just “what’s cheapest today” – it’s what level of protection lets you drive with confidence into the future.
Choosing Liability Limits Beyond the Minimum
Consider how fast $25,000 per person and $50,000 per accident could be exhausted in a serious injury crash on I-39: ambulance transport, emergency surgery, hospital stays, and months of physical therapy can generate bills well into six figures. If your liability limits are too low, you could be personally responsible for the difference.
Higher liability limits like 100/300/100 are recommended to protect personal assets – your home, savings, and wages. Compare actual quotes to evaluate the premium difference against potential uninsured losses.
When Comprehensive and Collision Usually Make Sense in Wausau
Comprehensive and collision coverages are not required by Wisconsin law but are advisable for newer vehicles and typically required by lenders for financed or leased cars.
For different vehicle situations:
-
New or newer cars driven on regional highways: Both coverages are strongly worth considering, given the replacement cost and exposure to highway-speed crashes and winter conditions.
-
Older paid-off vehicles used mostly around town: Weigh the annual premium against the car’s actual cash value. If the car is worth $3,000 and your annual comp/collision premium is $800, the math may not work in your favor.
-
Rarely used second vehicles: Consider whether you could absorb the loss out of pocket or whether even occasional use on rural roads justifies the coverage.
Balancing Budget and Protection
Wausau households can adjust deductibles, optional coverages, and limits to find a balance between monthly cost and protection level. An agent can prepare a couple of quote options – for example, a “lean but legal” option meeting minimums versus a “stronger protection” option with higher limits and lower deductibles – so you can compare side by side.
There is no one-size-fits-all answer. Each family’s income, assets, commute length, number of vehicles, and risk tolerance differ. Local discounts may include safe-driver, multi-policy, and low-mileage discounts – ask your agent what’s available. Claim handling reputation is crucial when choosing an auto insurance provider, so consider more than just price.
Driving and Parking Realities in Wausau
Understanding local driving patterns helps you make smarter coverage decisions. Here’s how Wausau’s roads and parking situations connect to insurance risk.
Commuting on US-51/I-39, Highway 29, and Local Arterials
Regional routes like US-51/I-39 and Highway 29 carry commercial through-traffic alongside local commuters heading to and from Wausau. Tell your agent about your routes, mileage and vehicle use when comparing coverage.
Higher speeds on Highway 29, particularly the expressway sections between Rothschild and Weston, can increase crash severity. Winter conditions compound the danger. This is why adequate liability, UM, and physical damage coverage matter for daily commuters.
Everyday city streets – Grand Avenue, Stewart Avenue, Bridge Street, and crossings over the Wisconsin River – see congestion, lane changes, and stop-and-go traffic that lead to fender benders. Even low-speed collisions can cause expensive damage to modern vehicles.
Rural Roads, Wildlife, and Weather
Many Wausau area residents live outside city limits and drive county highways and rural roads, especially in early morning or evening hours when deer and other wildlife are most active. Winter roads, visibility and wildlife are practical considerations when reviewing coverage for rural travel.
Remember: hitting a deer is usually a comprehensive claim. Weather-related damage – hail, falling tree limbs, ice damage – also generally falls under comprehensive, subject to your deductible and policy terms. Planning for winter means considering MedPay, UM, and adequate physical damage coverage, not just liability.
Parking in Downtown Wausau and Around Rib Mountain
Downtown parking structures, street parking on older blocks, and shopping center lots near Rib Mountain can see low-speed collisions, hit-and-run scrapes, and vandalism. Depending on the specifics, these events may involve collision coverage (for impact damage) or comprehensive coverage (for theft or vandalism).
Drivers should be familiar with official Wausau parking information to avoid citations. And always keep proof of insurance in the vehicle – you’ll need it if a minor accident requires a police report or information exchange.
Official Resources for Wausau and Wisconsin Drivers
Good insurance goes hand-in-hand with understanding state and local rules. Here are official, non-commercial resources worth bookmarking:
Key Wisconsin and Local Links
-
Wisconsin OCI Auto Insurance Guide – The official overview of required coverages, optional protections, claims procedures, cancellation rules, and consumer rights from the Office of the Commissioner of Insurance.
-
Wisconsin DOT Proof of Insurance / SR-22 – How SR-22 filings work, what the DMV requires, and what happens if coverage lapses during a required filing period.
-
City of Wausau Police Department – Parking Information – The official source for downtown Wausau parking rules and citation information.
-
Wisconsin DOT DMV Portal – For licensing, vehicle registration, and plate renewals, visit the main DMV website.
-
Drivers who commute between Wausau and other Wisconsin cities like Eau Claire, Green Bay, or Appleton can explore additional local guidance in the Wisconsin Cities section of our website.
Areas We Serve Around Wausau
WisconsinAutoInsurance.com serves drivers across Wausau and the broader Marathon County region by phone and online. No walk-in office – just direct access to an agent who can help you find coverage options that fit.
Wausau and Nearby Communities
-
Wausau (downtown, east side, west side, near Rib Mountain)
-
Rib Mountain
-
Schofield
-
Rothschild
-
Weston
-
Kronenwetter
-
Mosinee
-
Other Marathon County communities where residents live but work or shop in Wausau
The agency also helps drivers in other Wisconsin cities. Visit the Wisconsin Cities page for more local pages.
Frequently Asked Questions About Wausau Auto Insurance
These FAQs address common questions that delay Wausau drivers from requesting a quote or adjusting coverage.
How much does auto insurance typically cost in Wausau?
Costs vary based on driving record, age, vehicle type, garaging address, annual mileage, chosen coverages and limits, and credit information where allowed. The agency does not publish average prices or guarantee savings – instead, it helps compare available options tailored to each driver. Comparing quotes can help find the best auto insurance options for your situation.
What auto insurance coverages are required in Wisconsin?
Wisconsin requires at least 25/50/10 liability (bodily injury $25,000 per person, $50,000 per accident, property damage $10,000) and 25/50 uninsured motorist bodily injury coverage. MedPay must be offered but can be declined. Collision, comprehensive, and UIM are optional under state law, though lenders often require comp and collision for financed vehicles. Personal injury protection covers medical expenses after an accident in some states, but Wisconsin does not mandate PIP.
For more detail, see the Minimum Car Insurance Wisconsin page and the OCI auto insurance guide.
Do I need collision and comprehensive if my car is paid off?
State law does not require these coverages once the vehicle is paid off. But they may still be valuable if you cannot easily replace or repair the car after a major loss. Think about the vehicle’s actual cash value, local risks like deer strikes and hail in the Wausau area, and your personal budget. For an older car worth less than a few thousand dollars, the premiums may outweigh the benefit.
How does an SR-22 work for Wausau drivers?
The SR-22 is a certificate filed with Wisconsin DMV by an insurer to prove you carry at least the required liability coverage. The DMV – not the agency – decides how long the SR-22 is required. Confirm details on the DMV website or your official suspension/reinstatement notice. Canceling an SR-22 policy early may lead to another suspension.
Can I get insurance in Wausau if I have a recent accident or ticket?
Past incidents do not automatically make coverage impossible, but they can influence eligibility and rates. The agency often works with clients who have speeding tickets, at-fault crashes, or OWI history, and responsive support and great service still matter when drivers need help after a difficult event, but cannot guarantee acceptance or pricing from any insurer.
Does my auto insurance cover me when I drive to Eau Claire, Green Bay, or Appleton?
Standard Wisconsin personal auto policies typically follow the insured vehicle throughout the U.S. and sometimes into Canada, subject to policy terms. Regional trips to cities like Eau Claire, Green Bay, or Appleton are generally within scope. Review your policy or ask your agent for details if you plan longer trips or have special situations.
How do I show proof of insurance if I’m stopped by Wausau Police?
Keep a current insurance ID card – paper or digital, depending on current state acceptance – accessible to show law enforcement during a traffic stop or after a crash. Failure to provide proof can result in tickets or other consequences even if you actually have insurance. The minimum liability coverage for property damage is $10,000 and must be in force along with all other required coverages at all times.
Get Started with Wausau Auto Insurance Today
Whether you have a spotless record or recent tickets, are insuring a first car or handling an SR-22, WisconsinAutoInsurance.com offers locally informed guidance on Wisconsin coverages tailored to Wausau roads, weather, and commuting patterns. Every driver’s needs are different – and an independent agent can help you secure coverage that fits your life.
Call WisconsinAutoInsurance.com at (844) 317-1313 or begin a quote request to review coverage choices for your Wausau vehicle.
WisconsinAutoInsurance.com is operated by Drivers Insurance Agency, Inc., an independent agency. It is not affiliated with the Wisconsin Department of Transportation or the Office of the Commissioner of Insurance.