On this page
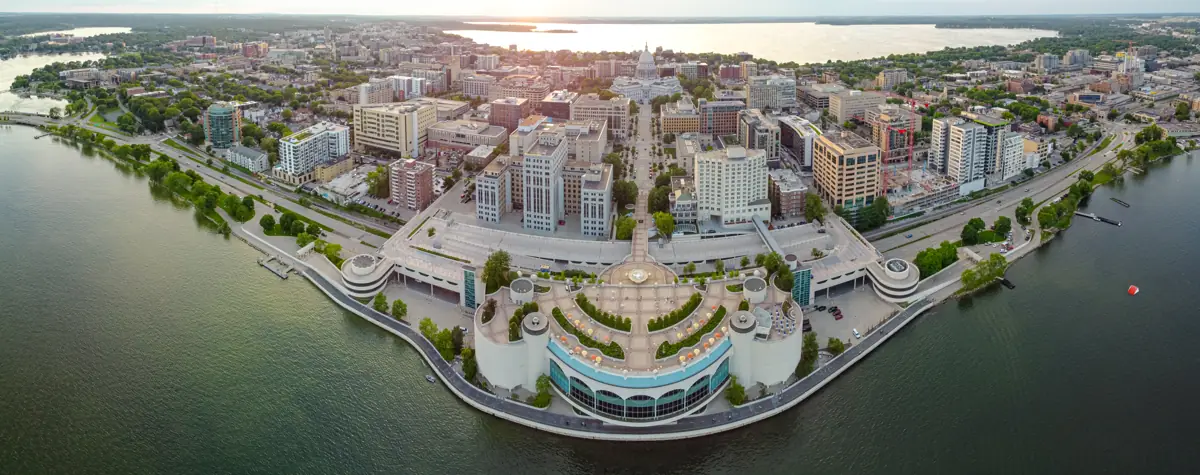
If you drive in Madison, WI, your insurance needs reflect specific local conditions: rush-hour congestion on the US 12/18 Beltline, interstate merges along I-39/90/94, tight parallel parking on the downtown isthmus between Lakes Mendota and Monona, and winter roads that turn icy without warning. Whether you are adding a student driver to your household policy, financing a new vehicle, or sorting out an SR-22 filing after a license issue, the right coverage starts with understanding what Wisconsin law requires and where Madison life creates extra risk.
WisconsinAutoInsurance.com (Drivers Insurance Agency, Inc.) is a licensed independent agency that helps Madison area households compare Wisconsin auto insurance options by phone and online. No office visit needed, no pressure to buy.
Request Your Madison Auto Insurance Quote
Call (844) 317-1313 or fill out our online quote form to get started. A quote request does not activate coverage; your policy begins only when the insurer approves and binds it with a confirmed effective date. Quotes are available for Madison commuters, students, households with past tickets or accidents, and drivers with clean records.
Why Madison Drivers Choose WisconsinAutoInsurance.com
Madison is not one kind of driving city. A Beltline commuter heading from Fitchburg to the East Side faces different risks than a UW-Madison student street-parking near campus or a retiree running errands on the Near West Side. As an independent agency, WisconsinAutoInsurance.com focuses on helping Madison households compare auto insurance options, since price and fit can vary by carrier.
About Our Agency
-
Drivers Insurance Agency, Inc. does business as WisconsinAutoInsurance.com and is licensed to sell auto insurance in Wisconsin. You can verify agency licenses through the Wisconsin Office of the Commissioner of Insurance website.
-
The agency serves Madison and surrounding communities entirely by phone and online, so you can compare quotes from home.
-
Coverage explanations on this page follow guidance from OCI’s consumer auto insurance materials.
-
This website focuses on Wisconsin auto insurance requirements and coverage choices.
What Sets Our Madison Auto Insurance Help Apart
Madison drivers care about staying legal on the road, protecting their vehicle from winter damage and parking lot incidents, satisfying lender requirements on financed cars, and keeping premiums within budget.
-
Tailored guidance for Madison commuting patterns on the Beltline, I-39/90/94, and cross-town routes where collision and higher liability limits often matter most.
-
Clear explanations of Wisconsin minimums vs. higher limits so your household can choose what fits its risk tolerance and budget rather than accepting a one-size-fits-all recommendation.
-
Experience helping drivers with tickets, accidents, or coverage gaps explore options, including policies that allow an SR-22 filing when required.
-
Support for situations unique to Madison: students sharing cars between campus and a suburban home, downtown apartment parking, and older vehicles used for local errands.
Madison Auto Insurance Coverage Options
Wisconsin sets a legal floor, but Madison conditions (Beltline traffic, isthmus parking, ice storms) often make additional coverage worth considering. The rules summarized here are based on the Wisconsin auto insurance requirements published by OCI. This section is informational, not legal advice; review your own policy and ask questions.
Wisconsin Liability Insurance: State Minimum vs. Madison Road Realities
Liability coverage pays for injuries and property damage you cause to others. Wisconsin law requires it. Wisconsin requires a minimum liability coverage of $25,000 per person for bodily injury, $50,000 for injury to multiple people in one accident, and $10,000 for property damage (25/50/10). Liability coverage is essential for Wisconsin drivers.
Property damage on a Madison highway illustrates the gap: $10,000 can be consumed by a single rear-end collision with a newer SUV on the Beltline, leaving you personally liable for the rest. Higher liability limits than state minimums are often recommended for better financial protection, especially for drivers who commute daily, carry passengers, or have assets at stake. Higher limits do not change fault determination; they increase what the insurer pays on your behalf up to the policy ceiling.
Uninsured and Underinsured Motorist Coverage
Madison drivers share roads with people who may carry only minimum limits or no insurance at all. Uninsured/underinsured motorist coverage is highly recommended for Wisconsin drivers.
-
Uninsured Motorist (UM) bodily injury is required in Wisconsin at minimums of $25,000 per person / $50,000 per accident. Uninsured motorist coverage protects against uninsured drivers.
-
UM in Wisconsin covers bodily injury only; it does not pay for damage to your vehicle. Physical damage to your car is addressed by collision coverage.
-
Underinsured Motorist (UIM) is optional. If you request it, minimum limits are $50,000 per person / $100,000 per accident. UIM can help when the at-fault driver’s bodily injury liability limits are lower than your UIM limits, subject to covered damages, policy terms, and applicable offsets.
-
Beltline commuters, carpoolers, and families with multiple passengers often consider higher UM/UIM limits because injuries from highway-speed crashes can generate large medical bills.
Medical Payments (Med Pay) for Madison Households
Wisconsin insurers must offer Medical Payments coverage, which you can accept or decline. Med Pay covers medical expenses for you and your passengers after a covered accident regardless of fault. If purchased, the minimum Med Pay limit is $1,000; available higher limits vary by insurer. For Madison families, Med Pay can bridge health insurance deductibles, help with costs after minor collisions near campus or downtown, subject to policy terms and coordination with health insurance. Ask how your policy applies if a household member is injured while walking or biking.
Collision vs. Comprehensive Coverage in Madison
Both are “physical damage” coverages protecting your own vehicle. Comprehensive and collision coverage are common auto insurance types.
Collision covers damage when your car overturns or hits another vehicle or object, subject to your deductible. Comprehensive (“other than collision”) covers theft, vandalism, fire, weather damage, hitting a deer on a Dane County highway, and glass breakage, also subject to a deductible. Comprehensive coverage protects against non-collision-related damages.
Lenders on financed or leased vehicles typically require both coverages even though Wisconsin law mandates only liability and UM. For older, paid-off cars parked on side streets near the isthmus, whether the vehicle’s value justifies the cost of these coverages is worth a direct conversation.
SR-22 Filings and Non-Owner Options
An SR-22 is a certificate of financial responsibility filed with the state on your behalf; it is not a type of insurance policy. WisDOT requires an SR-22 in specified circumstances, including certain revocations, occupational licenses, and financial-responsibility cases. A high-risk rating alone does not determine whether a filing is required. The requirement comes from the Wisconsin Department of Transportation or the courts, not from the agency.
WisconsinAutoInsurance.com can help many Madison drivers find policies that include an SR-22 filing when needed.
Non-owner auto insurance is designed for people who do not own a vehicle and do not have regular access to a household car but need liability coverage when occasionally borrowing or renting. Owning a car or having regular use of someone else’s vehicle generally disqualifies you. More detail is available on our SR-22 insurance page.

Auto Insurance for Common Madison Driving Situations
These scenarios are hypothetical, meant to illustrate how coverage decisions connect to real Madison life.
Beltline and Interstate Commuters
A driver using US 12/18 or I-39/90/94 daily faces peak-hour congestion, higher speeds, and frequent construction zones. Higher liability limits matter here because a multi-car collision at highway speed can generate bills well beyond 25/50/10. Collision coverage is relevant for any newer or financed vehicle exposed to that traffic daily. Many commuters park in employer lots or downtown garages, where comprehensive coverage addresses theft, vandalism, and storm damage. Learn more about minimum vs. broader coverage.
UW-Madison Students and Shared Household Vehicles
Students often share a car between a suburban home and a campus apartment. Listing all regular drivers on the policy helps avoid coverage disputes after an accident. A roommate who borrows a household vehicle regularly cannot rely on a non-owner policy for that access. Street parking in tight campus-area spaces raises the risk of fender benders and minor hit-and-run damage. Med Pay and UM/UIM matter for students who walk, bike, or ride as passengers frequently. Parents and students benefit from reviewing together who drives which vehicles, where each is parked, what any lender requires, and, if they are unsure what coverage makes sense, their options with a licensed agent.
Downtown and Isthmus Parking
Living or working between the lakes means parallel parking on narrow streets and in crowded lots. The City of Madison publishes street parking rules covering time limits, restricted zones, and metered spots, and downtown’s mix of restaurants, shops, and art traffic is one reason these streets stay busy. Frequent parallel parking and heavy pedestrian traffic increase low-speed collision and door-ding risk, making collision coverage and a reasonable deductible worth evaluating. Comprehensive coverage applies if your car is vandalized or stolen overnight on the street. Some drivers choose higher deductibles to manage premiums, but that means more out-of-pocket when damage occurs.
Winter Driving and Overnight Street Parking
Madison winters bring snow, ice, and freezing rain. The city’s alternate side parking and Snow Emergency rules affect where you leave your car overnight. The winter parking program is under review, so check the city’s page for current guidance rather than relying on fixed dates. Sliding into another car or a guardrail is a collision claim; falling branches, ice, and storm damage fall under comprehensive. Sudden windshield damage from flying debris may fall under comprehensive, subject to policy terms and any deductible; gradual wear or deterioration is not the same as an insured accident.
Older Cars Used Around Town
Drivers with high-mileage vehicles running errands on the Near West Side, East Side, or suburban neighborhoods still need liability and UM because injuries and damage to others can be expensive regardless of your car’s value. Minimum coverage in Wisconsin may leave drivers underinsured in an accident. Whether to keep collision and comprehensive on a paid-off older car depends on comparing the annual premium against the vehicle’s approximate worth. The agency walks you through that trade-off without pressure. Budget-focused drivers can also visit our cheap car insurance page.
How Getting a Madison Auto Insurance Quote Works
Requesting a quote is straightforward and can be done entirely by phone or online.
Step 1: Share Your Driver and Vehicle Details
Call (844) 317-1313 or complete the form at /quote/. You will typically need driver’s license numbers for household drivers, VINs, current coverages and limits (if any), and any recent tickets or accidents. Complete, accurate information produces more realistic quote options. Compare multiple quotes using equivalent coverage limits and deductibles; savings are not guaranteed.
Step 2: Compare Wisconsin Auto Insurance Options
A licensed agent reviews available options for your situation, helping you compare liability limits, deductibles, and required UM coverage and optional UIM, Med Pay, comprehensive, and collision coverage against your risk tolerance and budget, since available options and premiums can differ by carrier, not just by coverage choice. Auto insurance premiums vary based on age, driving record, credit history, and location. Wisconsin law allows insurers to consider credit history when pricing premiums. Telematics programs can offer discounts for safe driving habits in Wisconsin. Bundling auto insurance with homeowners or renters policies can lead to discounts. If you are unsure which limits or optional coverages fit your situation, a licensed agent can help you sort through them. Ask whether eligible multi-policy options are available for your household.
Step 3: Choose Coverage and Confirm Your Start Date
If you decide to move forward, the agent confirms coverages, limits, deductibles, and effective date with the insurer. Coverage does not begin when the quote is given or the form is submitted; it starts only when the policy is approved and bound. Insurers may cancel during a new policy’s first 60 days under Wisconsin rules, subject to applicable notice requirements, including at least 10 days’ written notice. Auto policies have no legally required grace period for late premiums. Ask your agent to confirm your exact effective date and payment requirements so there is no gap.
Quote Preparation Checklist for Madison Drivers
A bit of preparation makes the process faster.
-
Current auto insurance declarations page, if insured now (for apples-to-apples comparison)
-
Driver’s license numbers and dates of birth for all household drivers
-
Vehicle year, make, model, VIN, approximate mileage, and whether each car is financed or leased
-
List of any tickets, at-fault accidents, or claims in the last 3 to 5 years with approximate dates
-
Estimated daily commute distance and primary routes (Beltline, I-39/90, downtown isthmus, neighborhood only)
-
Where the car is parked overnight (driveway, garage, on-street downtown, campus area)
-
Any lender or lease company requirements about coverage or proof of insurance
Areas We Serve Around Madison
The agency works remotely by phone and online, serving drivers who live, work, or study in and around the Madison area.
-
City of Madison neighborhoods: downtown isthmus, Near West Side, Near East Side, North Side, South Side
-
Nearby communities connected by the Beltline and I-39/90/94: Fitchburg, Middleton, Monona, Verona
-
More local information for other Wisconsin cities: Sun Prairie, Janesville, and our full service area list
Frequently Asked Questions About Madison Auto Insurance
What auto insurance is legally required in Madison, Wisconsin?
Madison drivers follow Wisconsin state law: liability coverage of at least 25/50/10 and uninsured motorist bodily injury coverage of at least 25/50, per OCI. The City of Madison does not set separate auto insurance minimums. Review the OCI consumer auto insurance guide for detail.
Is the state minimum enough for driving in Madison traffic?
While 25/50/10 meets the legal floor, medical costs and vehicle repair bills after a Beltline or interstate crash can exceed those limits. The agency can show how different limit options affect premiums so you can choose what fits.
Do I need full coverage for my car in Madison?
“Full coverage” typically refers to liability plus comprehensive and collision. Wisconsin requires only liability and UM, but lenders commonly require comprehensive and collision on financed or leased vehicles. For older, paid-off cars, keeping those coverages is a personal decision based on the car’s value and your tolerance for risk.
How does an SR-22 work for Madison drivers?
An SR-22 is a filing proving you carry required insurance, not a policy type. Whether you need one is determined by WisDOT or the courts. WisconsinAutoInsurance.com can often help arrange policies that include an SR-22 filing for eligible Madison drivers. See our SR-22 insurance page for more.
Can I get non-owner car insurance if I live in Madison without a car?
Non-owner insurance is for people who do not own a vehicle and do not have regular access to a household car but need liability coverage when occasionally borrowing or renting. Owning a car or having regular use of someone else’s vehicle generally disqualifies you. Visit our non-owner SR-22 page for details.
When does my new Madison auto policy actually start?
Coverage begins only when the insurer approves and binds the policy with a specific effective date. Submitting a quote request or application alone does not activate coverage. Cancellation during the first 60 days remains subject to applicable written-notice requirements. Auto policies have no legally required grace period for late premiums. Confirm your exact effective date and payment requirements with your agent.
Get Started With Madison Auto Insurance Today
If you have questions about liability, UM/UIM, Med Pay, comprehensive, collision, or SR-22/non-owner options for your Madison household, call (844) 317-1313 or start an online quote. There is no obligation to buy. Decisions are always yours; the agency’s role is to explain your choices and help you connect with available options.
WisconsinAutoInsurance.com · Serving Madison, WI drivers by phone and online.